Insurance Fact Finding: Stop Collecting Data and Start Finding Out What People Really Want
Most agents were taught some version of insurance fact-finding.
Income. Assets. Debt. Current coverage. Retirement accounts. Mortgage balance. Kids.
Those numbers matter. You need them.
But here is the problem.
Numbers tell you what a client has. They do not tell you what a client wants.
I have sold insurance and coached agents for more than 30 years. In that time, I have watched agents fill out a perfect fact finder, write down every number on the page, and still walk out with nothing.
Why does that happen?
They collected information. They never found the reason behind it.
Good insurance fact finding is not a list of blanks to fill in. It is not a form you get through so you can run an illustration. And it should never feel like the client is being grilled.
It is a conversation built to answer one question:
What does this person really want, and why does it matter so much to them?
That is where every good insurance sales conversation starts.
What Is Insurance Fact Finding?
Insurance fact finding is how you learn a client’s money situation, goals, worries, priorities, current coverage, and reasons why before you ever suggest a product.
Here is the part most agents miss. There are really two fact finders happening in a good appointment.
The first one is about money. The second one is about feelings.
Most agents are decent at the first one. The second one is where sales get won or lost.
Money Facts and Heart Facts
Say you are sitting with a 42-year-old dad.
You learn:
- Income: $110,000
- Mortgage: $310,000
- Retirement savings: $185,000
- Life insurance: $250,000
- Two kids
That is useful. You need all of it.
Now picture learning this instead.
His dad died when he was 14. His mom had a hard time with money after that. He still remembers watching her work two jobs and come home tired.
His biggest worry is not dying.
His biggest worry is his wife and kids living through what he lived through.
That is a whole different talk.
The numbers tell you how much coverage might fit.
The story tells you why it matters.
You need both.
Why Most Insurance Fact Finding Falls Flat
The fastest way to lose a client is to make the meeting feel like paperwork.
Question. Answer. Write it down.
Next question. Answer. Write it down.
Next question.
You end up with a full page. The client ends up feeling like they just did their taxes.
That is not fact finding. That is data entry.
A real insurance sales conversation should feel normal, like two people talking. One answer should lead you to your next question.
And sometimes the best question is not even on your form. It is simply:
“Tell me more about that.”
Four words. They will open more doors than a whole page of money questions.
This Is What Consultative Selling Really Means
You hear the phrase consultative selling thrown around a lot. Here is what it comes down to.
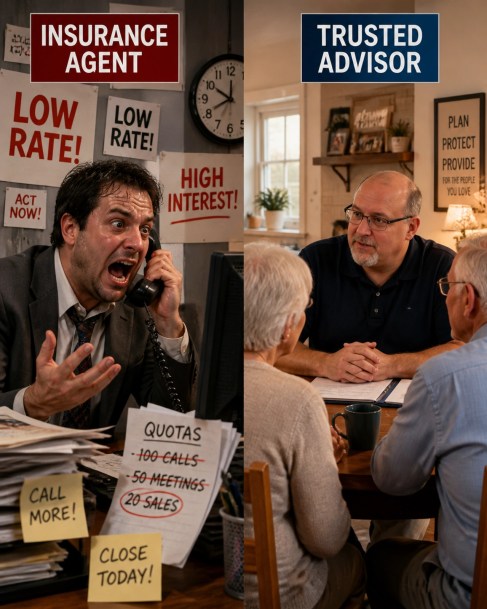
A salesperson shows up with a product and looks for someone to give it to.
A consultant shows up with questions and finds out what the person actually needs first.
Same appointment. Same products in the bag. Completely different experience for the client sitting across from you.
Fact finding is where that difference lives.
The Three Layers of Good Insurance Fact Finding
I teach agents to think about fact finding in three layers.

Layer 1: The Facts
Start with the basics.
What do they own? What do they owe? What do they earn? What coverage do they already have? What money could they get to in a pinch?
You need these answers to give honest advice. But do not stop here.
Most agents do.
Layer 2: The Goal
Now find out what they want.
Ask something like:
“What would you like to get done with your money over the next five or ten years?”
Maybe they want to:
- Pay off the house
- Take care of their spouse
- Build income for retirement
- Help with college
- Leave something to the kids
- Build up savings for emergencies
- Pay less in taxes
- Build cash they can get to later
Now you are getting somewhere.
But there is one more layer, and it is the one that matters most.
Layer 3: The Why
This is where the real conversation starts.
Ask:
“Why is that important to you?”
The answer may surprise you.
Nobody wants to pay off a mortgage because they hate mortgages. They may want it gone because they watched their parents lose a house.
Nobody wants retirement income because annuities are interesting. They may be scared to death of leaning on their kids someday.
Nobody buys life insurance because they want a death benefit. They want their husband or wife to be okay.
Products fix money problems.
People decide for personal reasons.
Good fact-finding ties the two together.
7 Insurance Fact-Finding Questions I Want Every Agent Asking
There are hundreds of insurance sales questions you could ask. These seven can change your appointments.
1. “What Made You Decide to Talk With Me?”
Do not assume you know.
Maybe they saw an ad. That tells you how they found you. It does not tell you why they picked up the phone.
Follow it with:
“What was going on that made you decide now was the time?”
Now you are getting to the reason.
2. “What Worries You Most About Money Right Now?”
Do not hand them a list to pick from. Let them answer.
You may be sure they are going to say retirement. Then they tell you they are losing sleep over credit card debt.
Listen to the answer they give you, not the one you were hoping for.
3. “If Something Happened to You Tomorrow, What Would Change for Your Family?”
This takes a risk that feels far away and makes it real.
Do not jump in with a fix. Let them sit and think about it.
Quiet is not your enemy.
4. “What Have You Already Done About It?”
Now you find out about their current coverage, savings, past agents, and old decisions.
Even better, you may find out why the last plan did not work. That tells you what to avoid.
5. “How Sure Are You That Your Plan Will Do What You Want It to Do?”
This question lets them grade their own plan.
You are not telling the client their coverage is weak. You are asking them to look at it.
That is a very different conversation, and it goes a lot better.
6. “If We Could Fix One Part of Your Money Situation, Which One Would Help the Most?”
Now you know what comes first.
Clients often have ten problems. You do not have to fix all ten today.
Find the one that matters most right now.
7. “Why Is Fixing That Important to You?”
This may be the best question on the whole list.
Ask it. Then be quiet.
Do not rescue them from the silence. Give them room to think.
What they say next is usually the reason behind every decision they make that day.
The Question After the Question
Here is a skill I want every agent to build.
Stop taking the first answer.
Watch how this works:
Client: “I want to have enough money for retirement.”
Agent: “Why is that important to you?”
Client: “I don’t want to run out.”
Agent: “What worries you most about running out?”
Client: “I don’t want to have to depend on my kids.”
Now you know.
Retirement was never the real issue.
Being independent was.
That one answer changes your whole presentation.
Don’t Turn Life Insurance Sales Questions Into Pressure
This part matters, so I want to be clear.
The point of asking about feelings is not to scare somebody into buying. That is pushing, and clients can smell it.
The point is to understand what a money decision really means to this family.
If you sell life insurance, dying is part of the conversation. If you sell retirement plans, running out of money is a fair thing to bring up. If you sell long-term care, needing help someday is a real issue.
You do not make those fears up. They were already there before you knocked on the door.
You simply give people room to say them out loud.
That is what a Trusted Advisor does.
Stop Building the Presentation in Your Head
This is hard for newer agents. I did it too.
The client says retirement. Your brain says, “I’ve got the perfect annuity.”
Stop. Keep listening.
They say they want to build cash. Your brain says, “IUL.”
Stop. Keep listening.
They say they want to leave money to the kids. Your brain says, “Whole life.”
Stop. Keep listening.
The second you start building the plan in your head, you check out of the conversation.
Clients can tell when you have left the room.
A doctor does not reach for the prescription pad in the first five minutes.
Finish figuring out the problem first.
How Better Fact Finding Cuts Down Objections
This ties directly into the related article, I Need to Think About It: What Your Prospect Is Really Saying.
Most objections are not made at the close.
They are just uncovered at the close.
When your fact finding is weak, here is what you hear:
- “I need to think about it.”
- “That’s more than I wanted to spend.”
- “I want to talk to my spouse.”
- “Just send me some information.”
When your fact-finding is strong, your advice is tied to something the client already told you was important.
Instead of saying:
“I think you need $750,000 of life insurance.”
You get to say:
“Earlier, you told me your biggest worry was making sure Michelle could stay in the house and the kids could still go to college. Let’s look at what it would take to make that happen.”
That is not a pitch.
That is simply the same conversation, still going.
Say It Back Before You Recommend Anything
Before you show a single number, stop and repeat what you heard.
Try this:
“Let me make sure I’ve got this right.”
Then tell them their own situation:
“Your biggest worry is making sure Susan doesn’t have to sell the house if something happens to you. You’d also like money set aside for the kids’ college. But you don’t want to put so much into insurance that it hurts your retirement savings. Did I get that right?”
Then stop talking.
Let them agree or correct you.
This does two big things.
First, it keeps you from solving the wrong problem.
Second, it proves you were listening.
Most people are not used to that. It sticks with them.
Ask Permission Before You Present
Once you know the problem, do not flip a switch and turn into a salesperson.
Ask:
“Would it be okay if I showed you a couple of ideas that might help?”
Almost everybody says yes.
But something important just happened.
They said yes.
You are not pushing a presentation on them anymore. They asked to see it.
Small move. Big difference.
Good Fact Finding Makes Your Presentation Shorter
Here is a quick test.
If your fact finding took ten minutes and your presentation takes an hour, you have it backward.
Strong discovery makes presentations shorter: not longer.
Why?
Because you do not have to explain everything. You only have to explain what they care about.

If the client wants income they can count on, do not spend 20 minutes on features they never asked about.
If they mainly want to take care of their spouse, do not bury them in every bell and whistle the policy has.
Show them the fix for the problem they told you about.
The Trusted Advisor Insurance Sales Process
Here is the insurance sales process I want you to remember. Seven steps, in order:
- Get the facts. What is their money situation?
- Get the goal. What do they want?
- Get the why. Why does it matter to them?
- Get the priority. What matters most right now?
- Say it back. Can you explain their situation better than they can?
- Ask permission. Are they ready to see some ideas?
- Then present.
Not before.
Your Challenge for Your Next Appointment
Do not try to memorize 50 new insurance fact-finding questions this week. You will forget them the second you sit down.
Start with three:
“What worries you most?”
“Why is that important to you?”
“Tell me more about that.”
Then listen.
Really listen.
You will find out things your old fact finder never would have turned up.
And once you know what your client actually wants, showing them the right plan gets a whole lot easier.
Common Questions About Insurance Fact Finding
What Is Insurance Fact Finding?
Insurance fact finding is how an agent learns a client’s money situation, goals, worries, priorities, current coverage, and reasons why before suggesting any product.
It covers both the numbers and the personal reasons behind them.
What Questions Should a Life Insurance Agent Ask?
Good life insurance sales questions cover income, debt, current coverage, dependents, and long-term goals.
Then follow up and ask why those goals matter.
The follow-up is where you learn the most.
Why Is Fact Finding Important in Insurance Sales?
Because it lets you make a recommendation based on what the client actually needs instead of what you guessed.
It builds trust, brings worries into the open early, and makes your presentation fit the person in front of you.
How Do I Ask Personal Questions Without Sounding Pushy?
Ask to understand, not to scare.
Find out how a loss would affect their family, why a goal matters, and what already keeps them up at night.
Do not invent problems, and do not steer them toward the answer you want.
Can Better Fact Finding Help Me Close More Sales?
Yes.
When your advice lines up with what the client told you they wanted, there is a lot less to argue about.
Most objections are simply questions you never asked.
Stop Collecting Facts. Start Understanding People.
A finished fact finder is not the goal.
Understanding the person across the table is the goal.
Numbers tell you part of their story.
Your questions tell you the rest.
When you put the money facts and the personal reasons together, you stop sounding like somebody trying to sell insurance.
You start sounding like somebody trying to help.
That is the difference between showing products and being a Trusted Advisor.
Want to Get Better at Fact Finding?
Inside the Insurance Pro Shop Membership, we work on what really happens at the kitchen table or on the Zoom call.
You get:
- Insurance sales training
- Fact-finding tools
- Question frameworks
- Scripts and worksheets
- Weekly live coaching
- Real appointment practice
Because knowing your products is not enough.
You have to know how to have the talk.
Become an Insurance Pro Shop Member
Learn more about Insurance Pro Shop and the systems, coaching, and training designed to help agents become trusted advisors.
Check out 2 live classes coming up
- Live In WEST PALM BEACH, FL – September 14th – Full Day Training – see details
- Online Classroom Training – September 26th and 29th – see details – only 10 slots available
Are You Asking Your Clients Enough Insurance Sales Questions? Only $39.95
By Coach Jeremy Nason, RFC®
 One of the recurring topics we write about each week… and talk about daily is asking your insurance prospects the right probing questions. And then ask your insurance prospects enough sales questions! That is because asking your prospects the right probing questions is one of, if not the biggest key to your success in selling insurance. Accordingly, agents have asked us for a complete list of probing sales questions to use with their insurance prospects! As a result, we have compiled a list of all of our favorite insurance sales questions. And we put them all into our limited edition e-book… Are You Asking Enough Insurance Sales Questions? In this 24-page guide, you will find our goldmine of probing questions you should ask your prospects to set appointments and close insurance sales. More Details!
Immediate Download… Order Now!
A huge key to finding and attracting exclusive leads, setting better appointments, closing sales, increasing your income, and successfully selling life insurance annuities and your services is and always will be getting the agent training to ask enough of the right sales questions!
“The key to a life insurance sale is an interview, and the key to an interview is a disturbing question.”